Buy to Let Mortgages for Every Kind of Landlord

From your first rental property to a growing portfolio, we find buy to let mortgages that work for your investment, and help you think through structure and tax with the benefit of in-house accountancy knowledge.

How Buy to Let Mortgages Work

Lending Based on Rent, Not Just Salary

A buy to let mortgage is designed for property you intend to rent out. Unlike a residential mortgage, the amount you can borrow is mainly determined by the expected rental income rather than your personal earnings.

Lenders apply an interest cover ratio, or rental stress test, to check that the rent comfortably exceeds the mortgage interest at a notional rate. Typical ratios range from around 125% to 145%, depending on the lender, the product and whether you are a basic or higher-rate taxpayer. Some lenders allow you to top up a shortfall with personal income.

Most buy to let lenders require a deposit of at least 25%, and many landlords choose interest only repayments to maximise monthly cash flow, with the plan to repay the loan from the eventual sale of the property.

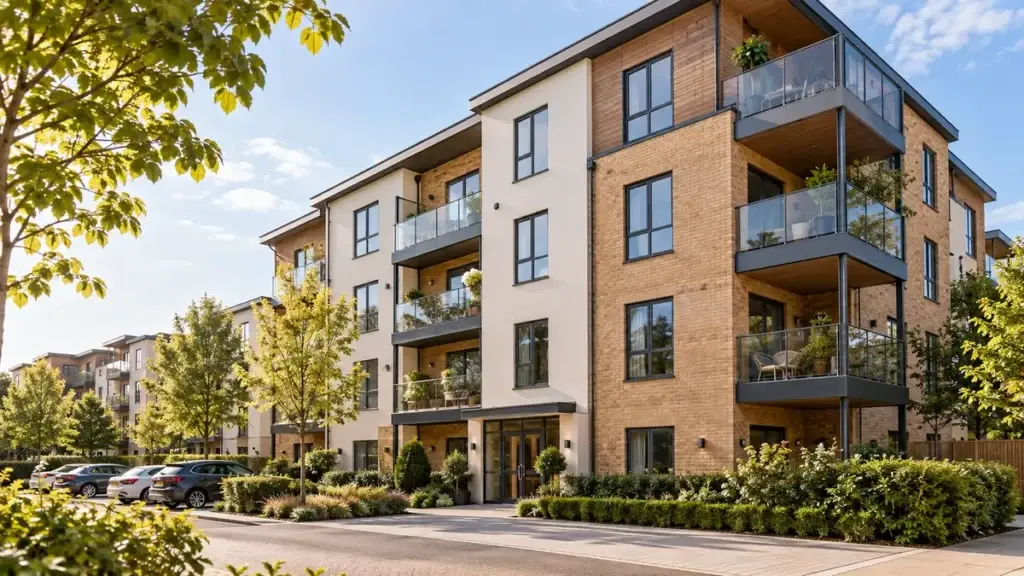
Contemporary low-rise apartment building with balconies
Landlords We Help

First-Time, Accidental and Portfolio Landlords

Laptop showing rental yield charts beside a model house, keys and a calculator
Personal Name or Limited Company?

Structure Matters, and So Does Tax

Since mortgage interest relief for individual landlords was restricted, many investors have looked at buying through a limited company. Companies can generally offset mortgage interest as a business cost, which can benefit higher-rate taxpayers. However, there are trade-offs, including different mortgage products, extraction of profits, and costs if you transfer existing properties.

This is one of the clearest examples of where our link with Futurewise Accountancy adds value. Our colleagues can provide tax advice on the right structure for you, while we arrange the finance that fits it. Joined-up advice means fewer expensive surprises.

Please note: Futurewise Finance does not give tax advice. Tax advice is provided separately by Futurewise Accountancy or your own accountant.

Row of red brick Victorian terraced houses with bay windows
Remortgaging Your Buy to Let

Keep Your Portfolio Working Hard

When a fixed rate ends, many landlords drift onto the lender’s standard variable rate without realising it. That can wipe out a significant share of your rental profit. We review your rental mortgages well before deals expire, compare product transfers with the wider market, and look at whether releasing equity could fund your next purchase or improvements to existing properties.

For landlords with several properties, we can carry out a full portfolio review: checking when each deal ends, how each property performs against current stress tests, and where refinancing could improve cash flow. Bringing deals onto a sensible timetable makes your portfolio easier to manage, and gives you a clear view of how much you could borrow for your next investment.

FAQs

Frequently Asked Questions

Usually at least 25% of the purchase price, although some lenders offer 20% deposit products, and better rates are often available at 40% or more.

Some lenders require a minimum personal income, while others rely mainly on rental income. Criteria vary, so it pays to get advice before applying.

Most are not regulated by the FCA, because they are business lending. Consumer buy to let, such as letting a former home or an inherited property, can be regulated.

Related pages

Explore more of what we offer

How it works

Working With Us Remotely

We work with clients in every corner of the UK, and almost all of our work is carried out online.

Free initial consultation

A short call or video meeting to understand what you want to achieve and what your finances look like.

Online meetings

Talk to your adviser by video or phone at a time that suits you, including [EVENINGS / WEEKENDS, CONFIRM].

Secure document upload

Send payslips, bank statements and accounts through our encrypted portal the moment you have them.

Electronic ID verification

Confirm your identity online in minutes.

E-signatures

Sign your paperwork digitally, from your phone if you like.